Trading signals often reach traders only after a noticeable price move has already happened, especially during breaking news or periods of high volatility. Modern markets process new information extremely quickly, while most signal systems need time to collect data, confirm conditions, generate an alert, and deliver it to users. Understanding the delay between an event, the market reaction, and the final trading signal is essential when evaluating whether a tool can provide practical value in real trading conditions.
Why markets often react before trading signals appear
Markets can begin repricing new information almost immediately, while many trading signals are generated only after that price movement creates a recognizable pattern. Large institutional participants, automated strategies, market makers, and news-driven algorithms continuously monitor data feeds and can react within fractions of a second.
Retail-oriented signal services usually operate further down this chain. They may wait for a candle to close, an indicator to cross a threshold, a breakout to be confirmed, or several conditions to align. By the time those requirements are satisfied, part of the market move may already be complete. This does not automatically make the signal useless, but it changes the price at which subscribers can realistically enter.
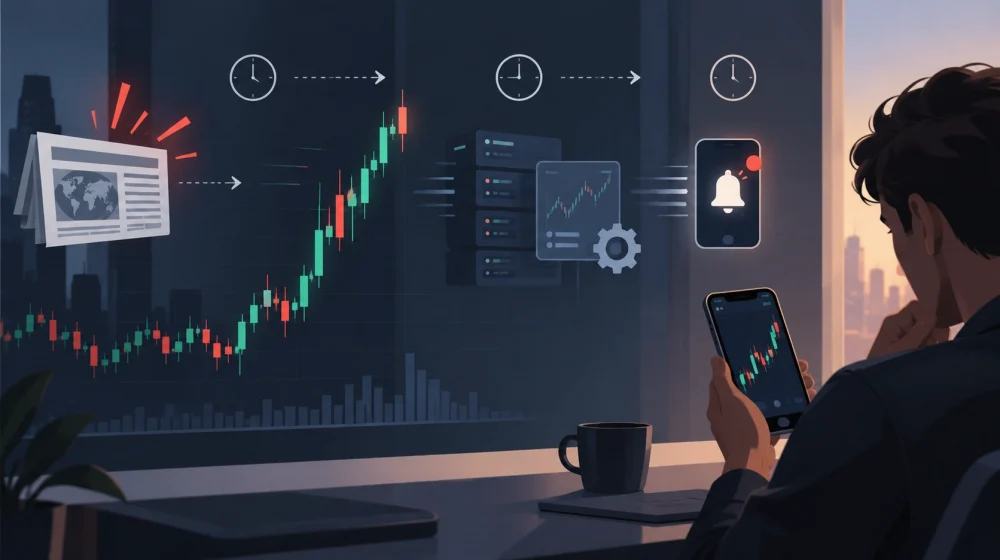
What happens between breaking news and a price move
The apparent instant reaction of a market is actually the result of several stages occurring extremely quickly. Understanding this sequence helps explain why a signal sent seconds or minutes later may already be responding to a changed market.
- New information becomes available. An earnings release, economic report, central-bank decision, geopolitical event, or company announcement reaches market participants.
- Automated systems and traders interpret the information. Algorithms may parse headlines, numerical data, or deviations from forecasts immediately.
- Orders enter the market. Participants begin buying, selling, cancelling existing orders, or changing quoted prices.
- Liquidity and price adjust. The order book changes as available liquidity is consumed and new bids and offers appear at different levels.
- The new movement becomes visible to signal systems. Indicators, chart patterns, volatility filters, and other tools begin reacting to the updated price data.
In highly liquid markets, these stages can unfold so rapidly that a human trader sees the price movement almost simultaneously with the news itself.
Where delays enter the trading signal process
Signal latency is rarely caused by one single delay; it usually comes from several small delays accumulating throughout the process.
- Market data delay. The provider must first receive updated prices, volume, order-flow information, or news data from its source.
- Indicator calculation. The system may need to process several periods of data or wait for specific technical conditions to be completed.
- Confirmation rules. Some strategies deliberately wait for additional evidence before generating a signal to reduce false entries.
- Platform processing. The provider’s servers need to create the alert, record it, and distribute it through applications, email, APIs, or messaging platforms.
- User reaction time. Even after an alert arrives, the subscriber still needs to see it, open a trading platform, evaluate the opportunity, and place an order.
Each individual delay may appear small, but together they can materially change the entry price during fast-moving conditions.
Why technical indicators are inherently backward-looking
Most technical indicators are calculated from historical or current market data, which means they confirm what price has already done rather than independently predicting the future. Moving averages, RSI, MACD, Bollinger Bands, and many momentum indicators use previous prices as inputs.
For example, a moving-average crossover can only occur after enough price movement has already changed the averages. Similarly, momentum indicators often become stronger as an existing move develops. This lag is not necessarily a flaw; it is part of the design. Waiting for confirmation can help filter noise, but the trade-off is a later entry.
Traders should therefore be cautious when a provider presents a technically generated signal as though it identified a move before the market reacted. In many cases, the signal was triggered precisely because the move had already started.
How algorithms and automated systems reduce signal latency
Automation can reduce the time between market data changes and signal delivery by removing many manual steps from the process. Algorithms can continuously monitor thousands of instruments, calculate conditions instantly, and generate alerts as soon as predefined rules are satisfied.
Direct data feeds, cloud infrastructure, low-latency servers, APIs, and automated execution tools can further reduce delays. Some advanced systems can also react directly to economic releases, order-book changes, or machine-readable news rather than waiting for traditional chart indicators.
However, reducing technical latency does not eliminate the underlying market reaction. Professional trading firms may have faster data connections, better execution infrastructure, and closer proximity to exchange servers than retail signal providers. A consumer-facing system can become faster, but it still competes in a market where other participants may react first.
Why faster signals are not necessarily better signals
Reducing delay can improve entry timing, but extremely fast signals may sacrifice confirmation and produce more false trades. Speed and reliability often involve a trade-off.
- More noise. Signals triggered immediately by small movements may react to temporary volatility rather than a genuine trend.
- Higher false-positive rates. Early signals have less confirming information available and may fail more frequently.
- Greater sensitivity to news spikes. Fast systems may enter during unstable price movements when spreads and slippage are unusually high.
- Less time for risk assessment. Traders receiving rapid alerts may feel pressure to act before evaluating position size, liquidity, and downside risk.
A slightly slower system that waits for better confirmation can sometimes produce more usable opportunities than one designed purely to be first.
How traders can evaluate the real-world latency of a signal service
The most useful latency measurement is the difference between the provider’s stated entry and the price subscribers could realistically obtain when the alert arrived.
- Record the signal timestamp. Note exactly when the alert appears on the platform or device.
- Compare market prices at that moment. Check whether the advertised entry was still available when subscribers received the signal.
- Track multiple signals. Evaluate latency across normal sessions, volatile markets, and major news events rather than judging one example.
- Measure execution results. Compare the provider’s published performance with realistic entries including spreads, slippage, and commissions.
If a service consistently reports entries that existed before its alerts reached users, its published returns may not represent achievable subscriber performance.
What signal delay means for real trading performance
Even a strong trading strategy can produce disappointing subscriber results if delays consistently worsen entry prices or reduce the remaining profit opportunity. A signal that originally targeted a 2% move may become far less attractive if the market has already moved 1.5% before the user receives it.
Late entries can also distort risk-reward ratios. Traders may enter closer to a profit target while the stop-loss remains relatively far away, creating a much less favorable trade than the original signal suggests. During volatile conditions, the problem can be amplified by wider spreads and slippage.
For this reason, traders should evaluate signal services using realistic execution rather than theoretical timestamps alone. Signal quality, speed, confirmation, liquidity, and risk management all matter together. The goal is not simply to receive alerts as quickly as possible, but to receive signals early enough to remain actionable without sacrificing so much confirmation that reliability collapses.